Fix & Flip and Ground-Up Construction LoansLet's get your deals funded.
CO. NMLS
#1326437
$200K – $5M
Loan size
12–18 mo
Loan term
660
Min. credit
Up to 90%
Max funding
How it works.
Tell me about your project.
Share the property, purchase or lot cost, renovation or build budget, and your exit strategy — selling or holding as a rental.
Establish your term.
We'll structure a 12–18 month term around your project. Exceptions can be considered — let's talk through your timeline.
Pay on what you use.
Interest-only payments on the funds you've drawn, not the unused portion of your loan.
Get reimbursed as you go.
An initial advance is released at closing. After that, request draws as each stage is finished — approved draws reimburse completed work and require paid invoices.
Tell me what you're working on. Let's structure it together.
Email meFunding based on experience & credit.
We're an exception lender. Our guidelines are a baseline, not set in stone. Send me what you have.
Fix & Flip
Structured on purchase price & rehab budget.
Any level of experience accepted.
- Experience
- Credit score (minimum 660)
- Assets
- Property (location, condition, age, etc.)
| Experience | Credit | Max % of total project costs |
|---|---|---|
| 0–2 Projects | 660+ | 80% |
| 3–5 Projects | 660+ | 85% |
| 3–5 Projects | 700+ | 90% |
Loan details & reserves
Interest reserves
Include up to 6–12 months of interest reserve payments in your loan, reducing out-of-pocket payments (based on scenario).
Fees & costs
Competitive rates. Fees and costs paid outside of close.
Eligible properties
Non-owner occupied single family to 2–4 unit. Investment properties only.
Exit strategy
Sell your property or hold for rental income. If holding, we can assist with refinancing or a take-out loan.
Assets required to cover
- Down payment
- 6 months of interest-only payments
- 10% of the renovation or construction budget set aside
Additional requirements
- Project costs may not exceed 70% of After Repair Value
- In some states, max funding is 65% of the property’s value after renovation
Draw review
We verify each request with a title rundown and inspections from the same engineering firm
Ground-Up requirements
Pre-qualification & builder review
As your Ground-Up Construction loan lender, we evaluate the builder’s experience, looking for at least three completed builds or a combination of two builds and one major renovation over $200K. Pre-quals are typically completed within 24 hours.
Project documentation
We collect approved construction plans, budgets, contractor agreements, and permits. This ensures the project is ready to move forward without delay.
Lot requirements
Must be “shovel ready” — grading, water, power hookups, etc.
Already own the lot?
Up to 65% of lot purchase cost can be advanced at close to cover closing costs and provide cash to start the project.
Soft costs
Permits, architectural plans and other essentials can be built into the budget.
Holding the property
DSCR or rental income should be roughly 1.0 — rental income roughly covers the loan payments.
Want to see where your experience and credit land you? Send me your deal.
Email meSee what you could qualify for.
Move the sliders to estimate your maximum leverage. Final terms depend on assets and the property.
Estimated max loan · 80%
$480,000
For illustration only. Not a loan approval, commitment, or offer to lend. Business-purpose loans only; all loans subject to underwriting, appraisal, and program guidelines, which may change without notice.
Like that number? Email me the deal and I'll firm it up.
Email meInvestment Property Program Details
1–4 UNIT PROPERTIES
- Loan amounts up to $5,000,000
- Purchase LTV up to 85%
- Rate-and-term LTV up to 80%
- Cash-out LTV up to 75%
- Cash-out available up to $500,000
- SFR, condos, non-warrantable condos, condotels
- DSCR ratios as low as 1.0x
- Available for 5-10 unit properties
ELIGIBILITY AND STRUCTURE
- LLC and trust vesting accepted
- No cap on properties owned
- Up to 10 loans per investor
- Multiple simultaneous closings
- Cryptocurrency accepted for reserves
- Transferred appraisals accepted
- 1031 exchange-compatible across non-owner occupied programs
RATE BUYDOWN AND STACKING
Discount points used to buy down the rate can be financed into the loan amount through our stacking feature, available across all investment programs. Borrowers get a lower payment without depleting reserves. Interest-only payment options are also available, which can meaningfully improve qualifying ratios in higher-rate environments.
Investment Lineup vs. Conventional
Where Our Investment Programs Win
Portfolio cap
Conventional/Fannie
Limits on financed properties
LendSure
No cap
Net rental losses
Conventional/Fannie
Added to monthly debt
LendSure
Deducted from income
Multiple loans, one closing
Conventional/Fannie
No
LendSure
Yes
LLC and trust vesting
Conventional/Fannie
Limited
LendSure
Yes
Non-warrantable condos
Conventional/Fannie
Rarely
LendSure
Yes
Condotels and STRs
Conventional/Fannie
Rarely
LendSure
Yes
DSCR (no personal income)
Conventional/Fannie
No
LendSure
Yes, 1.0x ratio
Cryptocurrency reserves
Conventional/Fannie
No
LendSure
Yes
Max loan amount
Conventional/Fannie
Agency limits
LendSure
$5,000,000
1031 exchange-compatible
Conventional/Fannie
Limited
LendSure
Yes, including DSCR
Comparison reflects our investment programs against conventional agency lending. Program details are subject to underwriting, appraisal, and program guidelines, which may change without notice.
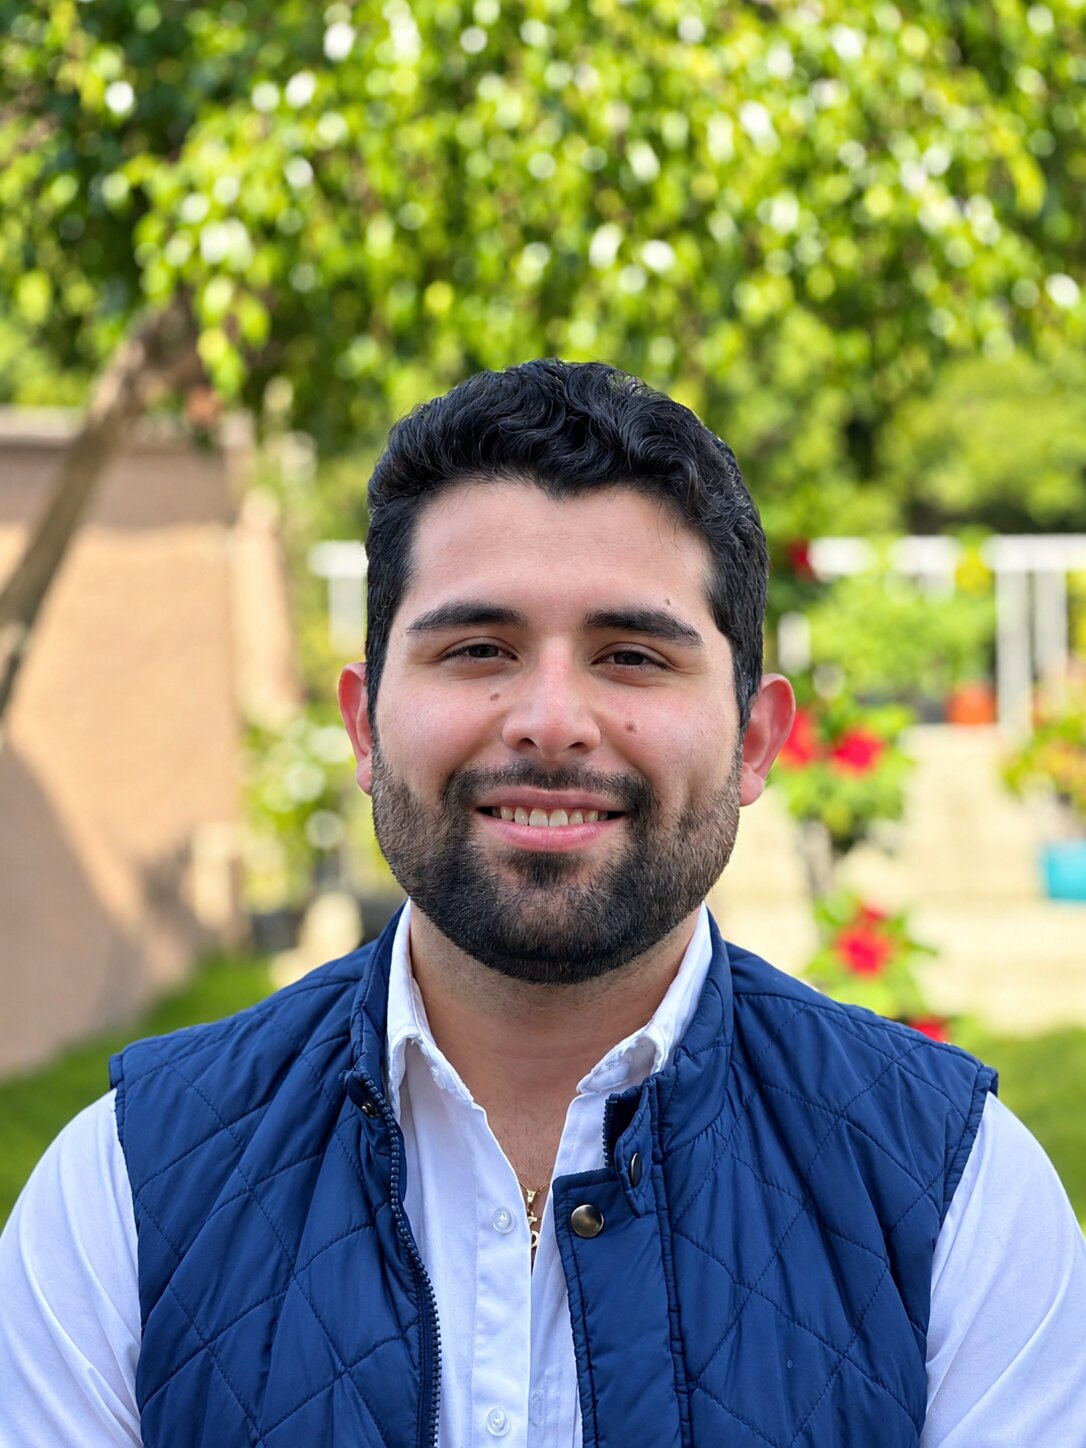
I've been on your side of the table.
Before I ever structured a loan, I was the one scrambling to fund my own deals. That experience is exactly why I do this the way I do.
01
Getting into real estate
Born and raised in Chula Vista, CA. I got into real estate in late 2017 and started my first business, Jet Set Home Offer — wholesaling distressed properties right here in San Diego. Before long I was working deals across the Midwest — Missouri, Nebraska, Tennessee, Kansas, you name it — and found real success in niche markets like Springfield, Missouri during the pandemic.
02
Going commercial
In 2022 I wanted bigger projects and larger spreads, so I went commercial — self storage, RV and mobile home parks, and everything in between, under EY Capital. Over 8+ years in real estate, I've been part of north of $14M in gross volume and served 60+ sellers, and learned how bigger deals get structured and funded.

03
Why lending
I spent years piecing together funding while under the gun, so I know exactly what it's like on your side of the table. Along the way I built an investor network of 5,000+ buyers and lenders. Now, as an Account Executive at LendSure Mortgage Company, I get to be the lending resource I always wished I had — someone who actually picks up the phone and finds a way to get the deal done.
Track record figures reflect J.P. Rivera's prior personal real estate activity through Jet Set Home Offer and EY Capital, which are independent of and not affiliated with LendSure Mortgage Company. Logos and website images shown for historical reference only. Past results do not guarantee future outcomes.
Have a Question? We Have the Answers.
Can a first-time investor use the DSCR program?
Yes. First-time investors can qualify on the DSCR program, though LTV will be more conservative than for experienced investors. The scenario is worth submitting. We evaluate each deal on its own merits.
How are gross rents determined for DSCR?
On a purchase, we use the rent survey from the appraisal or the operating statement on multifamily properties. When actual rents are higher than the appraiser’s market estimate, those higher rents can be used with lease agreements and two months of payment receipts to support them.
Is Airbnb income acceptable for DSCR?
Yes. Annual Airbnb statements are accepted for DSCR qualifying. Before structuring a loan around short-term rental income, confirm the property’s municipality and HOA permit short-term rentals. Restrictions vary by area.
Can the loan close in an LLC?
Yes. We accommodate LLC and trust vesting, which is particularly important for investors executing 1031 exchanges where the replacement property must be vested in the same entity that sold the relinquished one.
Can the rate be bought down without reducing cash reserves?
Yes. Discount points used to buy down the rate can be financed into the loan amount through our stacking feature, available on all programs. The borrower gets a lower rate without depleting liquid assets.
Is there a limit on how many properties an investor can own?
No. There is no cap on the number of properties a borrower can own. We can finance up to 10 loans for a single investor, and multiple loans can close simultaneously.
What happens if the DSCR ratio falls below 1.0x?
A ratio below 1.0x makes the loan more challenging but does not automatically disqualify it. Reach out to your Account Executive to walk through the specifics of the scenario.
How quickly can a file be reviewed?
Our team provides a thorough upfront income and credit review within 24 hours. No full file required to get started. Conditional approval typically follows within 48 to 72 hours of disclosure.
Do I need experience to get a fix and flip loan?
No. First-time flippers can qualify, though leverage is more conservative than for experienced investors. Strong credit and assets help offset limited experience, and the loan amount grows with your track record.
Do I need a property under contract to get started?
No. You can get pre-qualified before you have a deal, so you know your numbers before you make an offer. When the right property comes along, you can move fast.
Does the loan cover the renovation budget or just the purchase?
Both. The renovation budget is financed through a draw holdback and disbursed in stages as work is completed, so you are not funding the entire rehab out of pocket.
What do I need for a ground-up construction loan?
We look for a builder with at least three completed builds, or two builds plus one major renovation over $200K. You will also need project documentation such as plans, permits, and a budget.
What credit score do I need?
The minimum credit score is 660, but reach out anyway. We make exceptions all the time when the rest of the file is strong.
Have a question that's not on here? Send it my way.
Email meHave a project in mind? Let's talk.
J.P. Rivera
RTL Account Executive
LendSure Mortgage Corp. · Co. NMLS #1326437
Give me a call! Let's structure your deal together in a way that works for both sides.
LendSure Home Loans is a registered trade name of LendSure Mortgage Corp. NMLS ID# 1326437 (www.nmlsconsumeraccess.org). 12230 World Trade Drive, Suite 250, San Diego, CA 92128. 888.707.7811. All rights reserved. LendSure Mortgage Corp. is authorized to conduct business under the LendSure Home Loans trade name in Arizona, California, Georgia, Illinois, and Texas. Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms, and conditions are subject to change without notice. Equal Housing Lender.